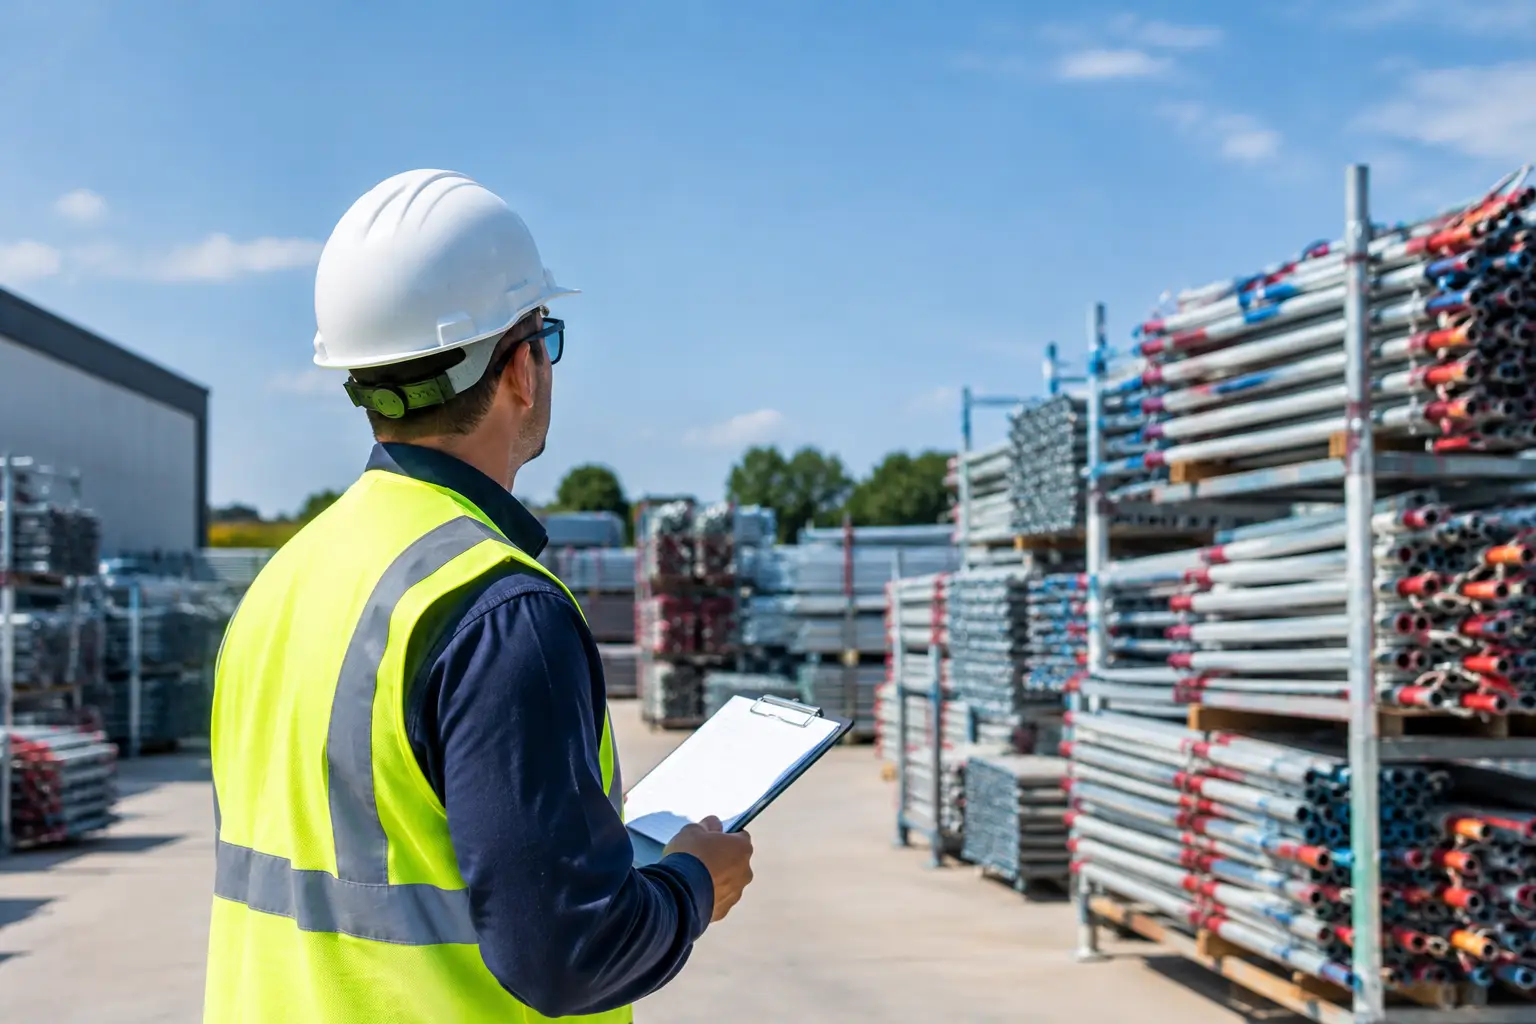
A scaffold yard can hold more value than it first appears. Tubes, boards, fittings, fencing, plant, lorries and tools can add up quickly – and one theft, fire or third-party injury can disrupt jobs for weeks. The best insurance for scaffold yards is not one off-the-shelf policy. It is a package built around what you store, who enters the premises and how your equipment moves from yard to site.
If you need cover that reflects the way your scaffolding business actually works, getting the details right before a loss matters far more than choosing the cheapest headline premium. Cover sorted today is useful. Cover that responds when your kit is gone or a claim lands is what keeps the business moving.
What makes a scaffold yard difficult to insure?
A scaffold yard is not a standard warehouse. It may be open-sided, remotely located or only lightly occupied outside working hours. Stock is often stored outdoors, loaded early in the morning and returned in varying quantities at the end of the day. There may be cutting, repairs, welding, fuel, forklifts or telehandlers on site. Then there is vehicle movement, deliveries and visiting contractors to consider.
Insurers will look closely at security, construction, access and the total value of equipment at the yard. They will also want to understand whether stock is left at customers’ sites, hired out, transported between jobs or kept in a separate lock-up. A policy that only covers contents within a locked building may leave a serious gap for scaffold materials stored in an open compound.
The right answer depends on the yard. A sole trader with a gated storage area has different needs from a contractor operating several vehicles, employing crews and holding significant stock across multiple locations.
The best insurance for scaffold yards starts with the right sections
A suitable policy normally combines several covers rather than relying on a single business insurance product. Each section should match the way your business operates.
Public liability for yard and site activity
Public liability insurance protects your business if someone is injured or their property is damaged because of your work or premises. At the yard, that could mean a visitor tripping over stored materials, a delivery driver being injured during unloading, or scaffold tubes damaging a neighbouring property.
For scaffolders, public liability must also reflect the work away from the yard. Erecting, altering and dismantling scaffolding carries obvious third-party risk, particularly around pedestrians, neighbouring properties and live construction sites. Many principal contractors and local authorities request evidence of cover before work starts. Where scaffolding encroaches onto a pavement or highway, proof of public liability may also be required for permit purposes.
Limits of £5 million or £10 million are common requests, but the required limit should be driven by contracts, locations and the potential scale of a loss. Do not assume a lower limit is enough simply because it costs less.
Employers’ liability for your crew
If you employ anyone, employers’ liability insurance is generally a legal requirement. This includes full-time staff and can include labour-only subcontractors, depending on the working relationship. It is designed to deal with claims where an employee suffers injury or illness arising from their work.
The exposure is not limited to working at height. Yard injuries can happen when loading a lorry, using plant, handling heavy boards or moving materials around uneven ground. Good procedures reduce the chance of an accident, but insurance provides financial protection if one still occurs.
Stock, materials and equipment at the yard
This is often the section that needs the closest attention. Ask whether the policy covers scaffolding materials and tools while they are stored in the open, in transit, at a temporary site compound and erected at a customer’s premises. The wording and conditions can differ significantly.
Be realistic about replacement costs. Scaffold stock has risen in price, and replacing a large quantity of tubes, boards and fittings after theft or fire can be far more expensive than the figure used when the policy was first arranged. Underinsuring may reduce a claim settlement, leaving you to fund the shortfall.
Theft cover often comes with security requirements. These may include perimeter fencing, locked gates, lighting, CCTV, alarms or specific locks for containers. If the policy says a condition must be met, treat it as part of the job – duct tape cannot fix a security warranty after a theft.
Own plant, hired plant and machinery
Forklifts, telehandlers, generators, compressors and other machinery need their own consideration. Plant may be owned outright, leased or hired for a particular contract. These are not always protected under a standard tools policy.
Own plant cover can insure specified machinery against accidental damage, theft and other insured events, subject to the policy terms. Hired-in plant cover is particularly useful where your hire agreement makes you responsible for loss or damage. Check the contract carefully: hire companies may hold you liable for continuing hire charges while equipment is unavailable, and this is not automatically included.
Fleet and commercial vehicle cover
Your vehicles are the link between yard and site. A lorry, van or pickup off the road can affect multiple jobs, especially when it is carrying the day’s scaffold load. Fleet or commercial vehicle insurance should reflect the vehicles you run, named or any-driver arrangements, business use and the carriage of tools and materials.
Do not assume tools or scaffold components in a vehicle are covered simply because the vehicle itself is insured. Goods in transit, tool cover and theft from an unattended vehicle can each have different limits and conditions.
Contract works and legal expenses
Contract works cover can help where materials intended for a job are damaged or stolen before the work is complete. It can be relevant for scaffolders supplying materials under contract, especially on larger or longer-running projects.
Legal expenses cover is different. It may provide support with certain disputes, such as contractual disagreements or employment issues, subject to the policy. It will not solve every argument, but it can give a smaller contractor access to professional help when a dispute threatens time and cash flow.
Questions to answer before you request a quote
Clear information leads to a more accurate quote and fewer surprises later. Before speaking to a broker, have your estimated stock values, turnover, wage roll, claims history and vehicle details to hand. It also helps to know the construction of your yard buildings, the type of perimeter security and whether materials are stored outside overnight.
Be upfront about the work you undertake. This includes maximum working heights, work over public highways, work on commercial sites, temporary roofing, specialist projects and any overseas work. Unlimited-height-risk options may be available for suitable businesses, but they need to be discussed rather than assumed.
Also explain how you use subcontractors. A bona fide subcontractor with their own insurance creates a different risk from a labour-only worker who operates under your direction. Getting this distinction right can affect both the cover required and the premium.
Where scaffold yard policies can fall short
The cheapest policy can be expensive if its definitions do not fit your operation. Common problems include low single-item limits for equipment, exclusions for theft from an open yard, inadequate cover for hired plant, and limits that do not allow for the full replacement cost of scaffold stock.
Another issue is relying on public liability when the loss is actually damage to your own property. Public liability is for injury or damage to others. It does not normally replace your own stolen tubes, burned-out container or damaged forklift. Those assets need appropriate property, stock or plant cover.
Read the excesses as well. A higher excess may reduce the premium, but it should remain affordable when a vehicle is damaged or a theft claim arises. For a small firm, agreeing to an excess that wipes out the value of smaller claims may not be worthwhile.
Practical ways to keep cover effective and costs sensible
Insurers reward well-managed risk because it reduces the likelihood and severity of claims. Secure perimeter fencing, controlled keys, lighting, CCTV and locked containers can all help, but only if they are maintained and used consistently. Keep an up-to-date asset register with photographs, serial numbers and purchase records where possible. After a theft, this can make identifying and valuing equipment much easier.
Good housekeeping matters too. Separate vehicle routes from pedestrian areas where practical, stack materials safely and keep access routes clear. Record inspections, driver checks and staff training. These steps are sensible for safety, and they also give useful evidence if an insurer asks how the business manages risk.
Review cover whenever the business changes. Buying another lorry, taking on employees, moving yards, winning a larger contract or investing in more plant can all make last year’s policy inadequate. A quick conversation before the change is easier than explaining an uninsured loss afterwards.
Scaff Cover can help arrange trade-focused protection across liability, vehicles, tools, plant and contract works, with an understanding of the working-at-height and yard risks scaffolders face. A specialist broker can also compare suitable market options and explain the detail in plain English, rather than leaving you to interpret a generic quotation alone.
The best policy is the one that lets you get on with the next lift, delivery and handover knowing the yard is not the weak point in your business. Start with accurate values, honest disclosure and a clear view of where your equipment sits overnight. That is how you turn insurance from a paperwork exercise into practical protection.