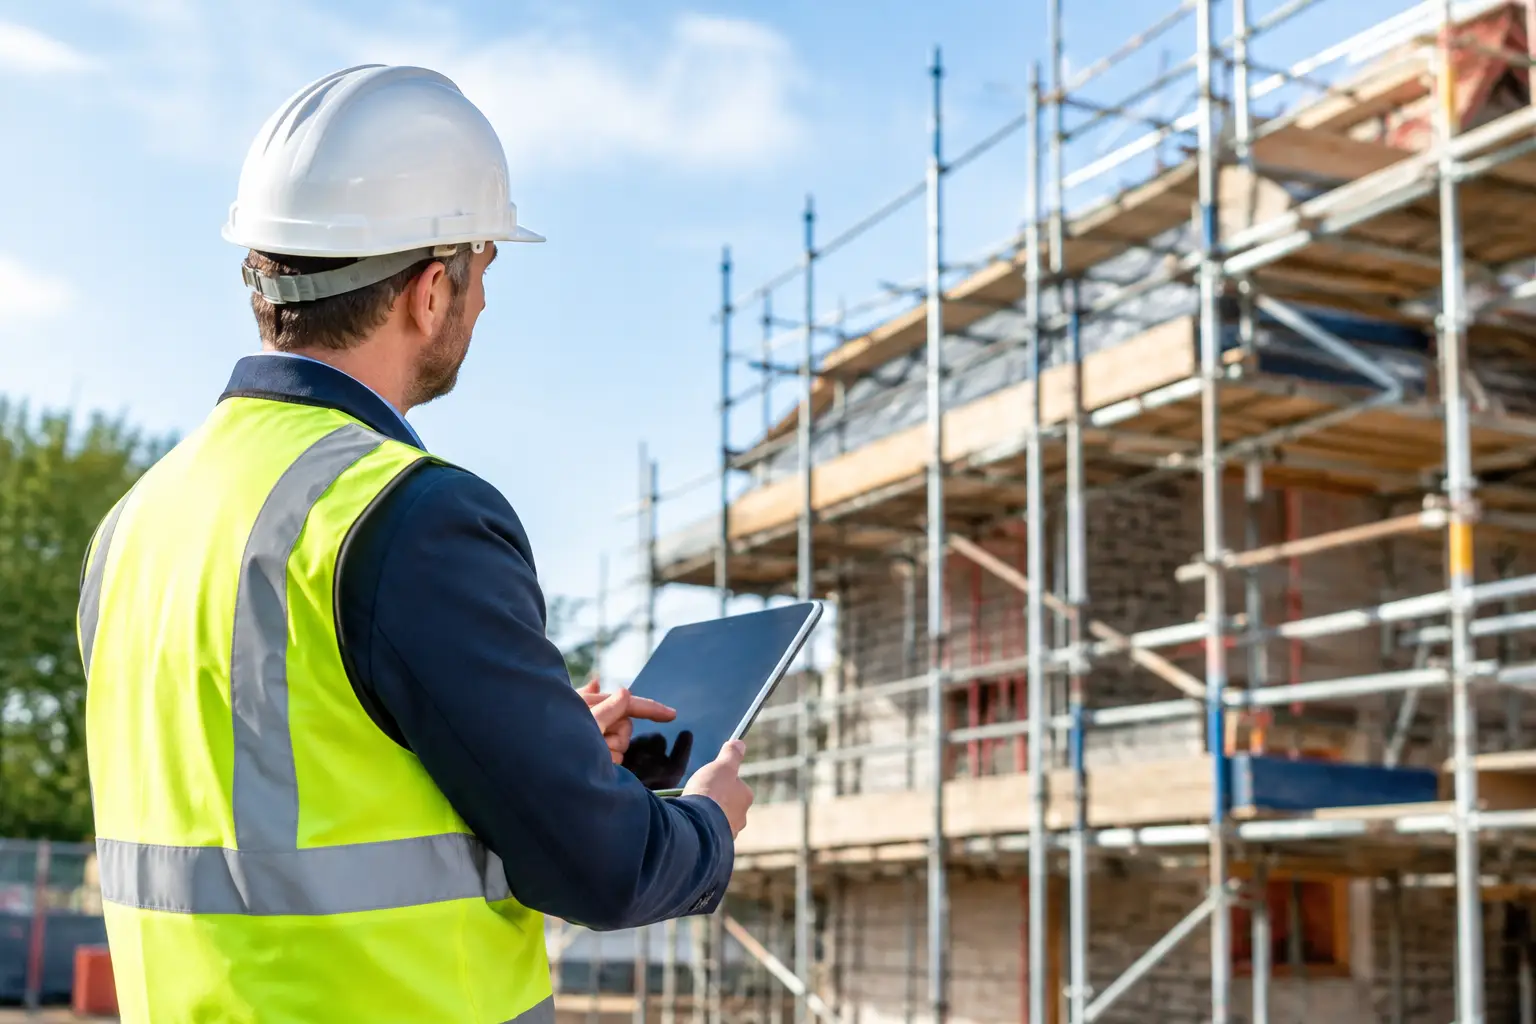
A scaffold risk assessment insurance guide should do more than help you tick a compliance box. It should show where a job could go wrong, who could be affected and whether your insurance would stand up to the financial fallout. When you are erecting, altering or striking a scaffold beside a busy pavement, over a shopfront or on a live construction site, the gap between a well-managed incident and a costly claim can be very small.
Cover sorted today starts with an honest view of the work you actually do. A one-man domestic scaffolder has different exposures from a contractor running several crews, lorries, hired plant and council-permitted pavement jobs. The aim is not to buy every policy going. It is to arrange protection that matches the risks your business carries.
Why risk assessments and insurance belong together
A risk assessment is a practical record of foreseeable hazards and the controls you will use. Insurance is there for the residual risk: the accident, loss or allegation that still happens despite sensible planning and competent work.
For example, your assessment may require exclusion zones during loading, tagged components, competent operatives, inspections and secure pavement barriers. Those controls reduce the chance of a tube falling or a member of the public walking into the work area. But if a falling fitting damages a parked car, or a pedestrian is injured, public liability insurance may be called upon to deal with compensation and legal costs, subject to the policy terms.
Insurers also want to understand that your work is properly managed. Clear method statements, training records, inspection routines and records of incidents can help demonstrate a professional approach. They do not guarantee a lower premium, but they can make it easier for a broker to present your risk accurately to insurers.
Start with the real job, not a generic form
A generic risk assessment copied from a previous contract rarely captures the details that affect both safety and cover. Before work starts, consider the specific site, the scaffold design, the sequence of work and the people around it.
Ask practical questions. Is the work on a narrow pavement or highway? Will materials be lifted over entrances, vehicles or public areas? Are you working near overhead cables, rail infrastructure, fragile roofs or schools? Is the ground capable of supporting the loading? Will the scaffold stay in place overnight, and can it be accessed by unauthorised people?
The answers can change your control measures and your insurance requirements. A contractor working on private domestic properties may need a very different liability limit from one working under a commercial principal contractor or local authority permit. Many contracts and permits specify minimum public liability limits, commonly £5 million or £10 million. The right limit depends on your contract and potential worst-case loss, not simply the cheapest option on a comparison screen.
Height is only one part of the exposure
Working at height is central to scaffolding, but it is not the only risk insurers consider. Manual handling, vehicle movements, public access, theft, hired equipment, defective materials and damage to property all matter.
Be upfront about maximum working heights, the types of scaffold erected, whether you undertake temporary roof work, and whether your jobs include confined sites or highway locations. If your policy has a height restriction that does not reflect your contracts, it could leave an unwelcome question at claim time. Specialist arrangements can include unlimited-height-risk options, but eligibility and terms will always depend on the insurer and the work declared.
The insurance covers a scaffolding risk assessment should prompt you to check
Public liability is usually the starting point. It covers your legal liability if your work causes accidental injury to a third party or accidental damage to their property. It can respond to scenarios such as a poorly secured board damaging a neighbour’s conservatory or an operative accidentally damaging cladding while erecting access scaffolding. It does not replace good site control, and it will not usually cover rectifying your own faulty work as a matter of course.
Employers’ liability is a legal requirement for most businesses that employ staff, including casual labour in many circumstances. It protects against claims from employees who are injured or become ill because of their work. There are limited exemptions, but do not assume a subcontractor arrangement removes the issue. Employment status, supervision and working practices matter. Check the position carefully if you use labour-only subcontractors.
Tools and equipment cover can protect the kit that keeps your crew earning. Scaffold components, hand tools and specialist equipment are attractive to thieves, particularly when stored in vans or at unsecured sites. Check single-item limits, security conditions, overnight vehicle requirements and whether hired-in kit is included. A policy that covers tools only at your registered premises is no help when the loss happens from a locked lorry at 5am.
Own plant and hired-in plant cover are relevant if you use vehicles, hoists, lifting equipment or machinery. Hiring kit can be efficient, but the hire agreement may make you responsible for loss or damage while it is in your custody. Do not assume public liability covers that contractual responsibility.
Motor fleet or business vehicle insurance should reflect how your vans and lorries are used, including carriage of scaffold materials and travel between sites. Legal expenses cover can be worth considering too. Contract disputes, debt recovery and employment issues can take time away from the job even where no major insured loss has occurred. Personal accident cover may provide a defined benefit if an insured person suffers a serious injury, but it is not a substitute for liability cover or income protection.
Contract works insurance is another conversation worth having where you are responsible for materials, temporary works or an ongoing project before handover. The contract wording decides who carries the risk. Never rely on assumptions made on site.
Turn controls into evidence
Good paperwork is not about creating a folder nobody opens. It gives your supervisors and crews a clear plan, while providing useful evidence if an incident is investigated.
Keep the risk assessment site-specific and make sure it is communicated to the people doing the work. Record scaffold inspections, handovers, alterations, training, toolbox talks, equipment checks and any changes in conditions. If a delivery route changes, wind conditions worsen or another trade creates a new hazard, revisit the assessment rather than carrying on with yesterday’s plan.
Photographs can be helpful, particularly for pavement barriers, signage, exclusion zones and the condition of neighbouring property before work begins. They should support sensible process, not become a distraction from supervising the job.
Avoid the common insurance gaps
The cheapest quote can be expensive if it has been built on incomplete information. Under-declaring turnover, employee numbers, payroll, contract values or working heights can affect how an insurer views a claim. So can failing to disclose past claims, prosecutions or material changes to your work.
Check whether your public liability policy includes the activities you carry out, rather than assuming the word “scaffolding” covers every variation. Temporary roofs, design responsibility, work on listed buildings, rail sites, petrochemical locations and work abroad can require specific consideration. Likewise, a client’s demand for an indemnity clause may go further than your policy automatically covers.
Read the excess as well as the headline limit. A higher excess can reduce the premium, but it must be an amount your business can meet without upsetting cash flow after a theft or minor damage claim. Paying by instalments can help spread the cost, although finance arrangements and total cost should be understood before you commit.
A practical insurance review before the next contract
Before accepting a new job, compare the contract and risk assessment with your current schedule of insurance. Check the liability limit, height and activity declarations, employee details, vehicles, plant, hired equipment and any client-specific requirements. If something has changed, raise it before work begins, not after an incident.
A specialist broker can help translate site realities into the questions insurers need answered, rather than forcing your business into a generic construction category. Scaff Cover arranges trade-focused cover for scaffolding businesses and can help make sense of the options, from liability and tools to fleet, plant and contract works protection.
Duct tape can fix a loose label, not an insurance gap. Give your risk assessment the same attention as your scaffold design, keep your records current and ask the awkward cover questions while there is still time to put them right.