Public Liability Insurance for Scaffolders
Published on: September 11, 2026
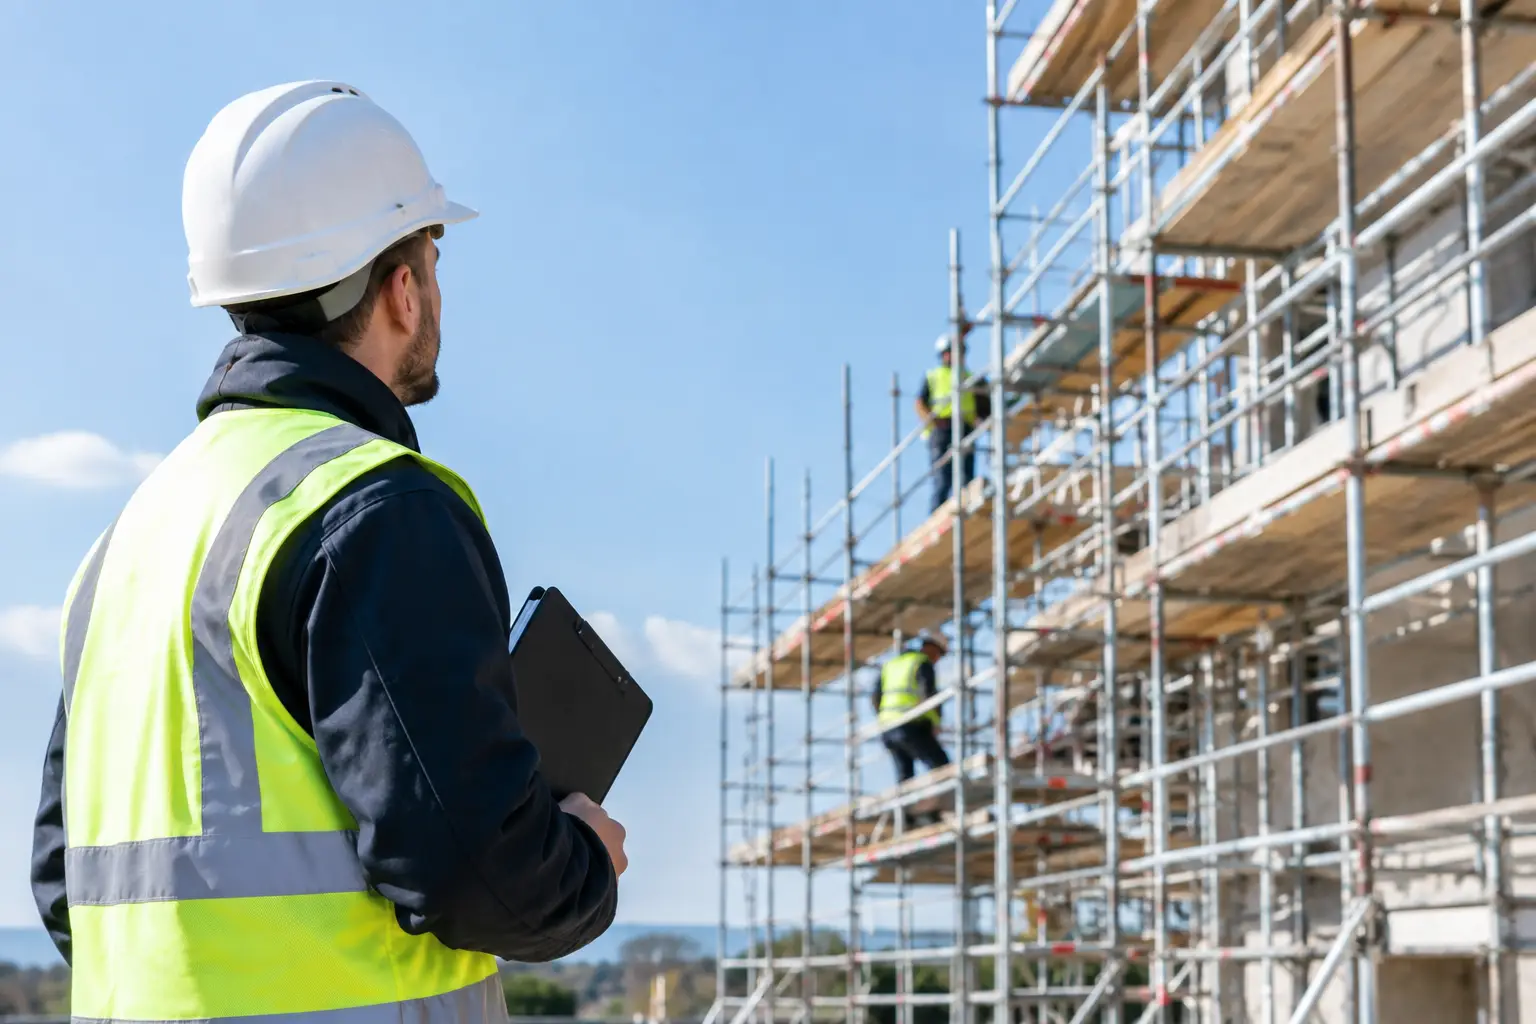
A dropped fitting, a damaged shopfront or a member of the public injured beneath a pavement scaffold can turn a normal working day into a serious claim. Public liability insurance for scaffolders is there to protect your business when your work causes accidental injury or damage to someone else’s property. Cover sorted before the job starts means less time worrying about paperwork and more time focusing on the work.
What public liability cover does for scaffolders
Public liability insurance can pay legal defence costs, compensation and associated expenses if a third party alleges that your business caused them injury or property damage. For scaffolders, that third party could be a pedestrian, neighbour, client, site visitor, passing motorist or another contractor.
The word “public” can be misleading. It is not just about people walking past a domestic job. A claim could arise when a lorry damages a client’s gate while materials are being unloaded, when a loose board damages a conservatory roof, or when a subcontractor says your scaffold created a hazard that led to an injury.
Scaffolding carries a particular level of exposure because the work combines height, heavy materials, changing sites and regular contact with public spaces. Even when your crew works carefully and follows site procedures, allegations can still be made. Defending a claim costs money, whether or not you are ultimately found liable.
Is public liability insurance a legal requirement?
Unlike employers’ liability insurance, public liability cover is not generally compulsory by UK law. In practice, many scaffolders cannot work without it. Principal contractors, local authorities, commercial clients and domestic customers may all ask to see proof of cover before allowing work to begin.
It is especially common to need a public liability insurance certificate when applying for a highway, pavement or road permit. The required limit may be set by the local authority or contract conditions. Do not assume that a policy accepted on one job will satisfy the next one.
A one-person scaffolder working solely on private premises may have fewer contractual demands than a contractor erecting street scaffolds across several boroughs. The principle is the same: the policy needs to match the work you actually undertake, not just meet the lowest figure on a tender form.
Choosing the right level of cover
Common limits are £1 million, £2 million, £5 million and £10 million. The correct limit depends on your clients, contract terms, location and the scale of the potential loss.
For lower-risk domestic work away from public highways, £1 million or £2 million may sometimes be accepted. Many commercial contractors and local authorities expect at least £5 million. Larger sites, city-centre projects, work near busy roads, rail infrastructure or valuable buildings can require £10 million or more.
The cheapest limit is not always the best value. If a contract requires £5 million and you hold £2 million, you may lose the job or have to arrange an amendment at short notice. Equally, buying a much higher limit than your work requires can add cost without adding practical benefit. A specialist broker can help you weigh up the contract requirement against the risks on site.
Height matters, but so do the policy terms
Working at height is central to scaffolding, yet not every liability policy treats it in the same way. Some policies apply a height restriction, while others can be arranged with unlimited-height-risk cover, subject to insurer appetite and the nature of your activities.
Read the schedule and wording carefully. Ask whether the policy covers the full range of work your business carries out, including erection, alteration, dismantling, temporary roof systems, design exposure where applicable, and work on or near highways. If your usual work changes during the year, tell your broker before taking on the contract.
What a scaffolder’s public liability policy may cover
A properly arranged policy is designed around accidental third-party injury and damage arising from your insured business activities. Typical scenarios include a pedestrian hurt by falling debris, scaffold components damaging a parked car, or accidental damage to a customer’s building while the scaffold is being installed.
It can also respond to the legal costs of investigating and defending an allegation. This matters because claims do not always arrive immediately. A person may report an injury weeks after an incident, or a property owner may identify damage once the scaffold has been removed.
There are limits to every policy. Public liability does not normally cover poor workmanship itself, the cost of redoing faulty work, deliberate acts, contractual liabilities you have accepted beyond your usual legal responsibility, or damage to property in your care, custody or control. Cover for such issues may be available in certain circumstances, but it should never be assumed.
For example, if a customer says a scaffold was erected incorrectly and needs rebuilding, the rebuild is unlikely to be a straightforward public liability claim. If that alleged defect causes part of a building to be damaged, the resulting damage may be considered differently. The detail matters, so report incidents early and avoid admitting liability on site.
Public liability is only one part of the picture
Duct tape cannot fix a gap in your insurance, and public liability alone will not protect every part of a scaffolding operation. If you employ anyone, including labour-only staff in many situations, employers’ liability insurance is usually a legal requirement. It protects against claims from employees who are injured or become ill because of their work.
Your vehicles need appropriate motor or fleet insurance, whether you run a single van or several lorries. Tools, scaffold stock, own plant and hired-in plant may need separate cover for theft, damage or loss. Contract works insurance can be relevant where materials, temporary works or a project are damaged before handover. Personal accident cover can provide financial support following an injury, while legal expenses cover can help with certain disputes.
Packaging these covers together can make administration easier, but there is a trade-off. A bundled policy is only useful if the individual limits, excesses and exclusions work for your business. It is worth reviewing the detail rather than choosing a package solely because the headline premium looks attractive.
Information insurers will want to know
Accurate information helps insurers assess the risk fairly and avoids problems later. Expect questions about turnover, the number of workers, wage roll, work at height, types of contracts, claims history, postcode areas, use of subcontractors and whether you work on highways or public pavements.
Be clear about who does what. A bona fide subcontractor operating independently is treated differently from a labour-only subcontractor working under your supervision. If you provide design, calculations, inspections or sign-off, say so. If you install temporary roofs, access towers, hoists or undertake work near railways, airports or water, raise it at quote stage.
Do not underestimate turnover to reduce the premium. Insurers may use turnover as a measure of how much work you do, and a material difference can complicate a claim. The same goes for past incidents. A well-explained claim history is usually better than an undisclosed one.
Reducing claims and keeping cover workable
Good risk management does not just protect people. It can support cleaner claims records and give insurers confidence in how your business operates. Keep inspection records current, train crews properly, secure materials, use suitable exclusion zones and make sure public-facing signage and lighting are in place where required.
For pavement and roadside scaffolds, confirm permit conditions before work starts. Those conditions may deal with lighting, pedestrian management, protective fans, hoardings, width restrictions and inspection requirements. A permit does not replace insurance, and insurance does not replace compliance with the permit.
When an incident happens, photograph the area where safe to do so, retain relevant documents, record witness details and notify your insurer or broker promptly. Do not promise payment or accept fault simply to calm an unhappy client. A quick, factual report gives the claims team the best chance to protect your position.
Getting cover that reflects the job
Public liability insurance should be arranged around the reality of your work: the heights involved, the streets you occupy, the equipment you use and the contracts you want to win. Before comparing quotes, have your turnover, claims details, workforce information and upcoming project requirements to hand. It makes the process quicker and reduces the chance of buying cover that looks fine on paper but falls short on site.
Scaff Cover can help scaffolders compare trade-specific options, including arrangements for unlimited height risks where available, and make sense of the limits clients and local authorities ask for. The right question is not simply “How cheap is the policy?” It is “Will this policy stand up when the job, the client and the unexpected incident put it to the test?”