Scaffolding Fleet Insurance Any Driver Explained
Published on: September 16, 2026
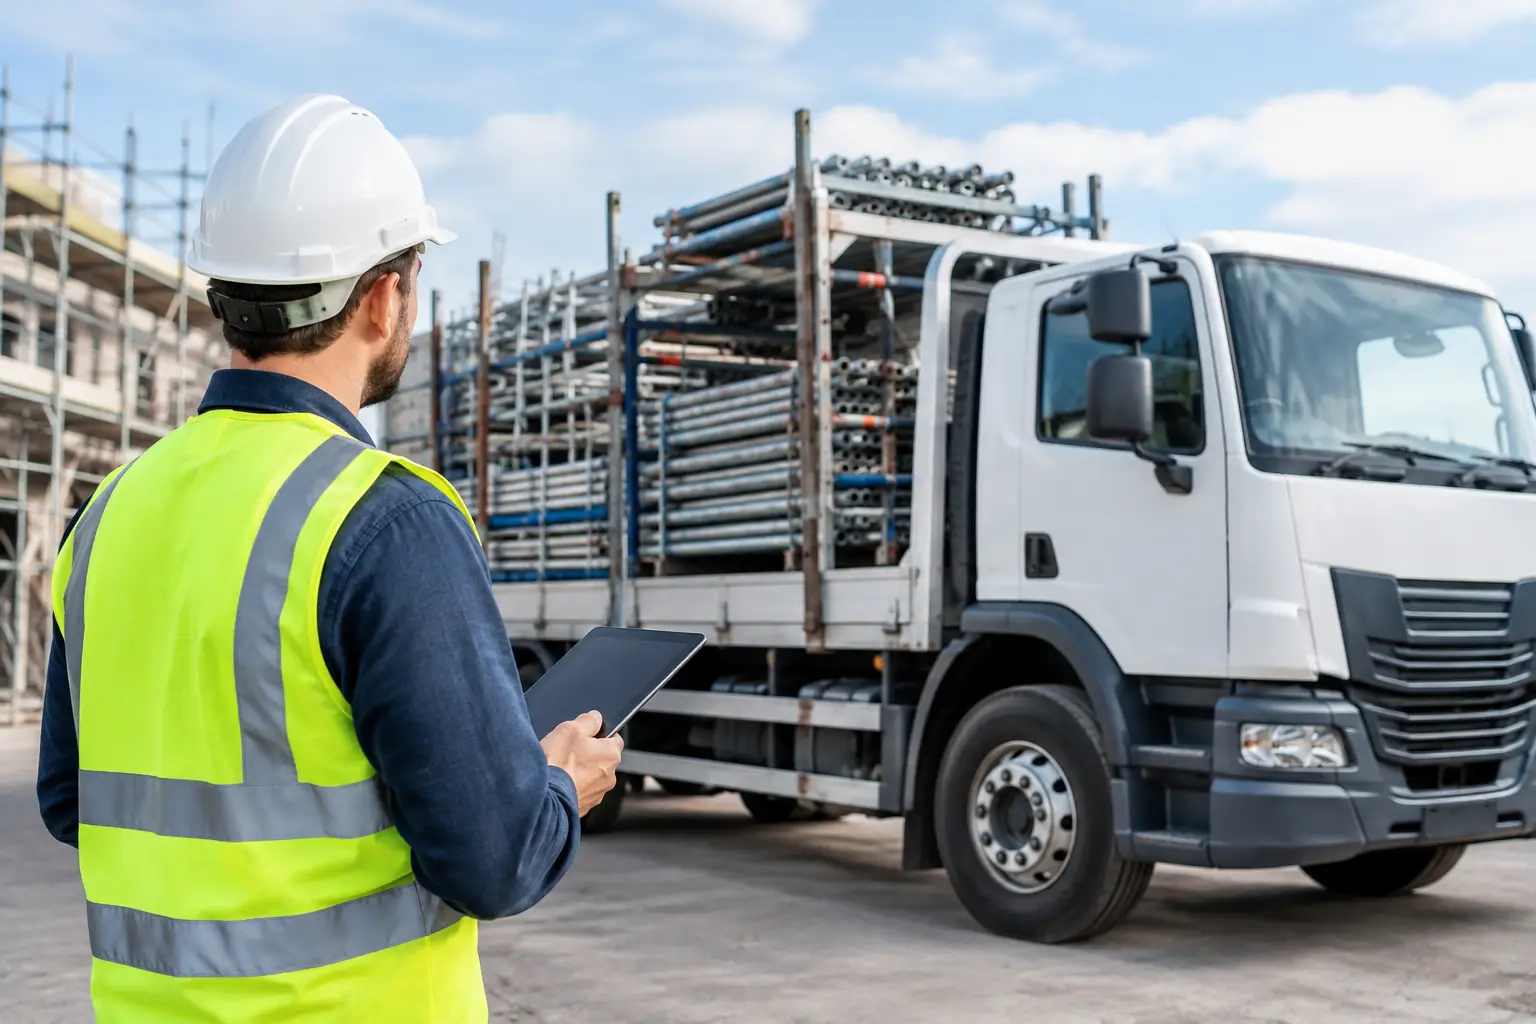
A van is rarely driven by the same person every day in a scaffolding business. One operative may collect fittings before dawn, a supervisor may move between jobs, and a labourer may take a vehicle back to the yard after a late strike. That is why scaffolding fleet insurance any driver arrangements can be appealing. They can reduce the need to amend a policy whenever duties change, but the wording still matters just as much as the convenience.
The key point is simple: “any driver” does not normally mean every person who asks for the keys. It usually means any driver who meets the insurer’s agreed conditions. Getting those conditions right can protect the vehicles that keep your jobs moving, without paying for flexibility you do not genuinely need.
What does any-driver fleet cover mean?
A fleet policy insures two or more business vehicles under one policy, rather than arranging separate cover for each van, pick-up or lorry. An any-driver extension allows qualifying people to drive vehicles in the fleet without being individually named.
For scaffolding contractors, this can suit a workforce that changes from site to site. A driver may be needed at short notice to move boards, tubes, ladders or tools, collect hired equipment, or respond when another vehicle is off the road. It can also make administration easier where directors, foremen and regular employees share vehicles.
However, insurers will set an age range, licence requirements and experience rules. A common restriction might be drivers aged 25 and over with a full UK licence and no serious motoring convictions. Younger drivers, employees with recent claims, or anyone with convictions may need to be declared separately, accepted on different terms, or excluded altogether.
The policy schedule, not the label “any driver”, is what decides who can drive. Assuming cover is in place is a costly mistake when a vehicle is damaged, stolen or involved in a third-party injury claim.
When scaffolding fleet insurance any driver makes sense
Any-driver cover is most useful when vehicle use is genuinely shared and operational flexibility has a clear value. A growing firm with several crews, a busy yard and multiple active sites may find it difficult to keep named-driver records current. If a driver is off sick or a job overruns, another suitably qualified team member can take over without a last-minute policy amendment.
It can also be practical for firms using a mixture of transit vans, dropsides, pick-ups and heavier vehicles. The person allowed to drive each vehicle still needs the correct licence entitlement. Insurance does not make someone legally entitled to drive a 7.5-tonne lorry, tow a loaded trailer, or operate a vehicle with a particular weight category.
There is a trade-off. Broad any-driver terms can cost more because the insurer has less control over the risk. If the same two or three people drive every vehicle, named-driver cover may be better value. Some businesses take a middle route: named drivers for most vehicles, with a carefully restricted any-driver basis for selected vans. The right approach depends on how often drivers change, the value and type of vehicles, claims history, and the age and experience of the people behind the wheel.
The cover levels to consider
Every vehicle used on the road needs at least third-party insurance. For a working scaffolding fleet, third-party only is rarely the full answer. It pays for injury or property damage caused to others, but it will not pay to repair or replace your own vehicle after an at-fault accident, fire or theft.
Third-party, fire and theft adds protection if a vehicle is stolen or damaged by fire. Comprehensive fleet cover goes further, typically including accidental damage to your own vehicles. That matters when a damaged van means missed deliveries, idle labour and a crew unable to reach site.
Ask how the policy treats the items that are part of the job, not just the vehicle itself. Racking, roof racks, beacons, signwriting, tow bars and specialist storage can affect the insured value. Tools and scaffolding equipment carried in a van may not be covered automatically under motor insurance, particularly where theft occurs overnight or equipment is left unattended. Separate tools, plant or goods-in-transit protection may be needed depending on what is carried and why.
Breakdown assistance, replacement-vehicle options and windscreen cover can be equally useful. They will not prevent an accident, but they can limit disruption after one. Check the limits, excesses and whether the replacement vehicle is suitable for carrying the equipment your crew needs.
Do not overlook vehicle use and site access
A scaffolding vehicle does more than commute. It may carry long materials, collect hired plant, deliver tools, tow trailers or enter construction sites with restricted access. Tell the broker how vehicles are used, where they are kept overnight and whether they travel nationwide. Routine travel to several jobs is different from private social use, and both may need to be included if employees take vehicles home.
Loading and unloading is another area worth discussing. Motor cover deals with road risks, but a claim involving falling materials, a pedestrian, or damage while unloading can cross into public liability territory. Your motor, public liability and employers’ liability policies should work together rather than leave an awkward gap.
For heavier vehicles and specialist use, insurers may ask about driver training, tachograph compliance where applicable, daily walkaround checks and load security. These are not box-ticking exercises. A loose load can cause serious injury, damage a client’s property and put your contract at risk.
Practical steps that can help control premiums
Insurance pricing is based on the details of your business, so there is no single cheap answer. But clear fleet management gives insurers a better picture of the risk and can help avoid preventable claims.
Keep a driver record showing licence checks, endorsements, training and who is authorised to use each class of vehicle. Repeat checks regularly, not just at recruitment. Put a simple process in place for reporting new convictions, accidents and vehicle damage promptly.
Secure vehicles at the yard and at drivers’ homes where possible. Alarms, immobilisers, trackers, lockable storage and sensible key control can all be relevant, especially where vehicles carry valuable tools. Insurers may apply theft conditions, so make sure the way vehicles are actually stored meets the policy requirements.
Daily checks should cover tyres, lights, mirrors, brakes, fluid levels, body damage and load restraints. Encourage crews to report defects before they become roadside failures. A short record of inspections and maintenance can also be valuable evidence if a claim or liability question arises.
Finally, be accurate about claims. An undeclared bump, theft or driver conviction can cause issues later, even if it seemed minor at the time. Honest information may affect the premium, but it gives your broker the best chance of finding suitable terms from the outset.
Questions worth asking before you buy
Before accepting a fleet quotation, ask whether every regular driver is eligible under the any-driver wording and what happens if you take on an apprentice or younger employee. Confirm the excess for each type of claim, including theft and windscreen damage, and whether excesses differ for younger or higher-risk drivers.
You should also establish whether vehicles are covered for towing, carriage of your own tools and materials, travel between sites, and use by employees at home. If you run both vans and larger vehicles, check that each class is correctly listed. A fleet schedule should reflect the business you operate now, with a clear route for adding or removing vehicles as jobs and crews change.
A flexible fleet still needs firm controls
Any-driver fleet cover can be a sensible way to keep a scaffolding operation moving when crews, sites and duties change at short notice. It works best when the flexibility is matched by clear driver rules, proper licence checks and cover built around the vehicles and equipment you actually use.
A specialist broker such as Scaff Cover can talk through those practical details, compare available insurer terms and help arrange cover that fits your working pattern. The useful next step is not simply asking for “any driver” cover. It is setting out who drives, what they drive, where they work and what a vehicle off the road would cost your business. That is how you turn a convenient policy feature into protection that stands up when the job gets busy.