Scaffolding Insurance for Pavement Permits
Published on: September 21, 2026
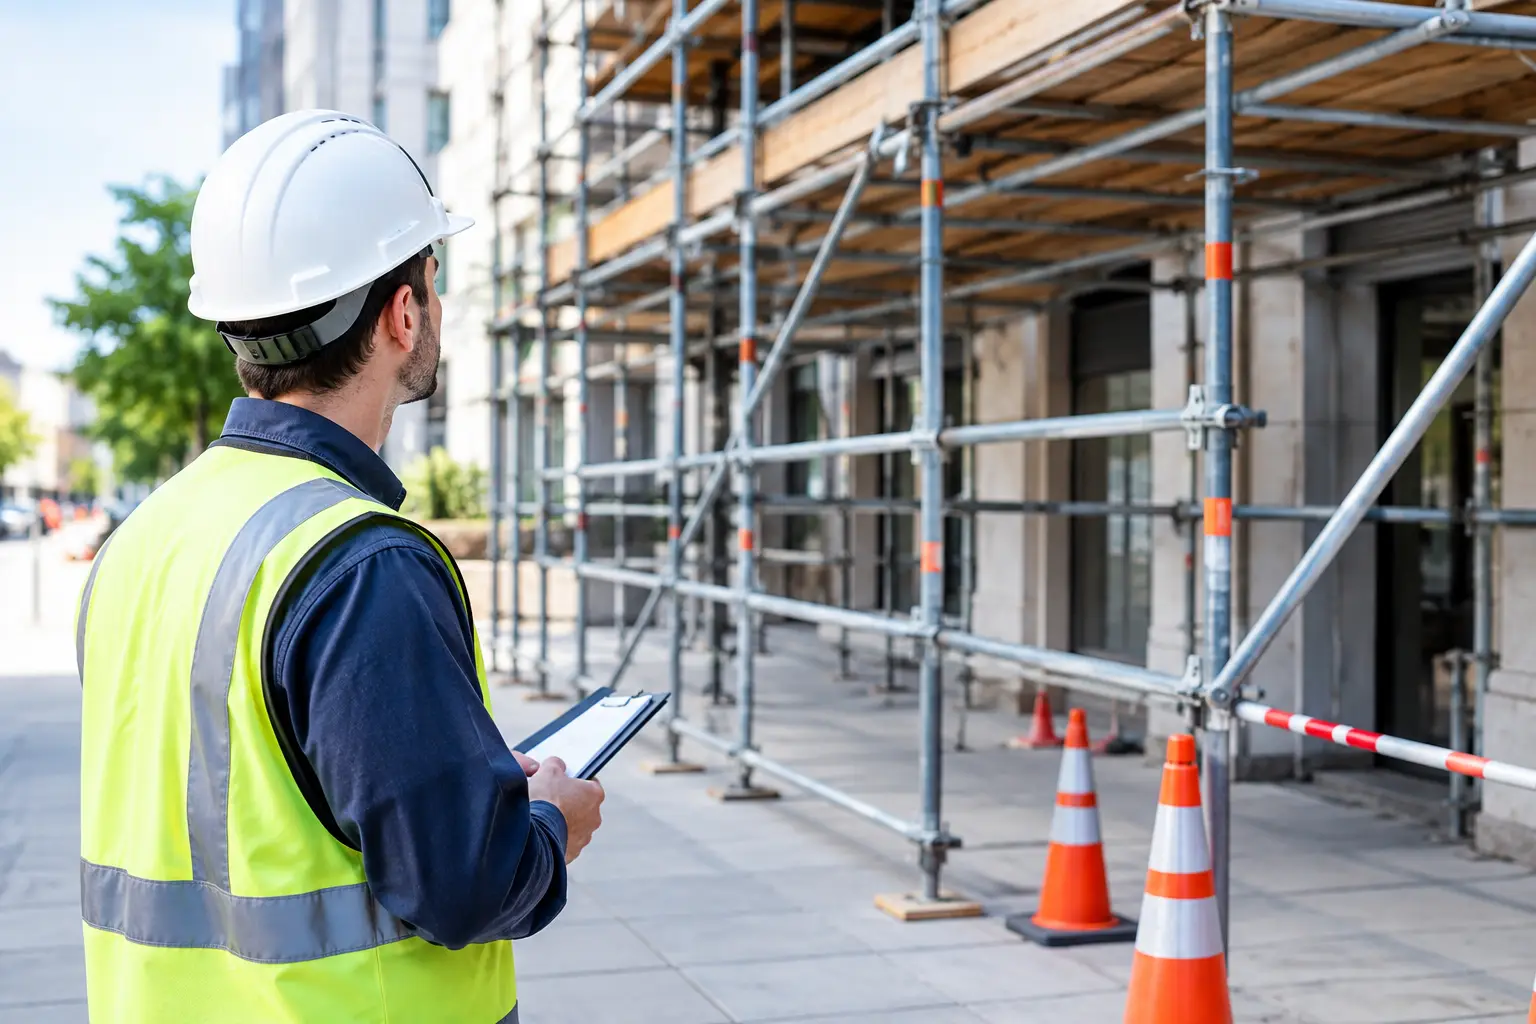
Need a pavement permit for a scaffold that will sit on a public footway or road? The council will usually want proof of suitable scaffolding insurance for pavement permits before it considers the application. Getting the paperwork wrong can hold up the job, frustrate your client and leave a crew standing by with nowhere to erect.
The practical answer is to check the permit conditions before the scaffold arrives, not after. Councils set their own requirements, and the right public liability limit, policy wording and certificate dates can make the difference between a straightforward approval and a last-minute problem.
Why councils ask for insurance before issuing a permit
A pavement licence or scaffold permit is needed when scaffolding, hoarding, towers, skips or associated equipment occupy part of the public highway. That can include the footway, carriageway, verge or pedestrian area outside a domestic or commercial property.
The council is not taking on the risk simply because it has granted permission. It wants reassurance that, if a member of the public is injured or their property is damaged because of the scaffold, the contractor has insurance in place to meet a valid claim. The exposure is greater than on a fenced private site. Pedestrians pass beneath and around the structure, vehicles may be working close by, and the public can be affected day and night.
A loose board, a poorly protected base plate, a falling fitting or restricted access to a shop can all create a potential third-party claim. Even where the allegation is unfounded, dealing with it can take time and money. That is why public liability cover is normally the central insurance requirement for a pavement permit.
What insurance do you normally need for a pavement permit?
Most local authorities ask for a current public liability insurance certificate. The required indemnity limit varies by council and location. £5 million is a common starting point, while £10 million may be required in busier town centres, on main roads or under certain council contracts. Never assume the limit accepted on one job will be accepted on the next.
Public liability insurance is designed to cover compensation you become legally liable to pay for accidental injury to a third party or accidental damage to their property, together with related legal defence costs where covered by the policy. For pavement work, that could mean a passer-by tripping on an inadequately marked obstruction, a vehicle being damaged by materials falling from the scaffold, or damage caused while loading out.
The certificate needs to be valid on the dates the scaffold will be erected and remain on the highway. If the job runs over, tell the council where required and make sure your insurance has not expired or been cancelled. A permit is not a substitute for an active policy.
Public liability is not the whole insurance picture
A permit application may focus on public liability, but the wider job can involve other exposures. If you employ labourers, scaffolders or apprentices, employers’ liability insurance is generally a legal requirement. It responds to claims from employees who suffer injury or illness in connection with their work.
Your own tools, tubes, boards and fittings may need tools and equipment cover, while hired lifting equipment or specialist plant may require hired-in plant cover. A lorry or van used for the job needs the right motor insurance for its use. Contract works cover can also be relevant where your contract makes you responsible for scaffold materials or works in progress.
These covers do not usually replace the public liability certificate requested by the council. They protect different parts of the operation. Duct tape cannot fix a gap in the policy schedule, and neither can a pavement permit.
Check the council’s permit conditions first
Every highway authority can set its own application process, fees, lead times and insurance requirements. Some ask for a copy of the policy certificate only. Others may ask for details of the indemnity limit, the scaffold company, site address, erection and removal dates, drawings, traffic management arrangements or a licence application submitted by the property owner.
Read the conditions closely, particularly if the scaffold affects a controlled parking bay, loading area, cycle lane or busy pedestrian route. The authority may specify lighting, reflective markings, fan protection, pedestrian barriers, minimum walkway widths and inspection requirements. Insurance supports your financial protection, but it does not remove the need to comply with the licence conditions or work safely.
It also pays to establish who is named on the permit. The principal contractor, building contractor, property owner and scaffolding contractor may all have different responsibilities. If a client applies in their name but your business erects the scaffold, make sure the arrangement is clear and that your insurer has the correct nature of your work. Do not send a certificate that belongs to another business and assume it protects you.
Getting your insurance evidence ready
When a job is due to start, speed matters. Keep an up-to-date public liability certificate available in a format you can send promptly to the council, client or principal contractor. Check that it shows the insured business name correctly and displays the required indemnity limit.
Before submitting it, confirm four practical details:
- The policy is active throughout the permit period.
- The business name matches the permit application and trading details.
- The public liability limit meets the authority’s stated minimum.
- The description of your business reflects scaffolding work, including the type of contracts you undertake.
If the council asks for a higher limit than you currently hold, do not alter a document or hope the application slips through. Speak to your broker. Depending on your policy and the insurer’s terms, increasing the limit may be possible, but it needs to be arranged properly and confirmed in writing.
The detail that can catch scaffolders out
The phrase “working at height” can cause confusion when arranging cover. A pavement permit itself does not determine whether your insurance is suitable for the job. The key questions are the height, location, type of structure, access arrangements, work being carried out and any insurer restrictions in your policy.
For example, a straightforward domestic scaffold over a quiet pavement is not the same risk as a large commercial scaffold beside a live road, over a public entrance or around a railway-facing elevation. A policy with a low height restriction or unsuitable activity wording may not be right just because it has a £5 million public liability limit.
Likewise, be accurate about specialist work. Temporary roof systems, cantilever scaffolds, pavement gantries, protection fans and work near highways can change the risk profile. Good advice starts with the real job, not the cheapest headline premium.
There is also a difference between having insurance and admitting liability. If an incident happens, secure the area, record what has occurred, retain photographs and site records, and notify the relevant parties in line with your policy terms. Do not make promises about compensation at the roadside. Let insurers and claims specialists assess the circumstances.
Reduce the chance of a claim while the scaffold is on the highway
A strong insurance policy is there for when things go wrong. The day-to-day aim is to stop them going wrong in the first place. Clear pedestrian routes, suitable barriers, correct lighting and regular inspections are not paperwork exercises when the public is walking past the site.
Think about the job outside working hours too. A scaffold may be perfectly managed while the crew is present but more vulnerable overnight, during high winds or when deliveries are taking place nearby. Confirm that access points are secure, signs remain visible, loose materials are not left where they can fall or be moved, and the public cannot easily climb the structure.
Keep a clear record of inspections, alterations and handovers. If there is a complaint or an incident, these records can help show that the scaffold was erected, checked and maintained responsibly. They also help you identify issues early, before they become a costly claim or a permit breach.
Scaffolding insurance for pavement permits: ask the right questions
When arranging or reviewing cover, tell your broker that your scaffolds may occupy pavements or highways. Mention the usual contract values, number of employees, maximum working heights, locations, hired equipment and whether you work on domestic, commercial or public-sector sites. The clearer the picture, the more useful the advice.
Ask whether the policy has any height limits, activity exclusions, excesses or conditions that could affect the work you take on. Ask how quickly certificates can be issued when a council needs evidence. And if you regularly require £10 million public liability for tenders or permit applications, build that into your insurance planning rather than treating it as an emergency every time.
Scaff Cover can help scaffolders compare trade-relevant options and arrange evidence of cover without the usual run-around. The right policy is not simply one that gets a permit approved. It is one that reflects the work your crew actually carries out when the pavement is busy, the schedule is tight and there is no room for guesswork.
Before the next scaffold goes up, put the permit conditions and insurance certificate side by side. A few minutes spent checking the names, dates and liability limit can keep the job moving and give you one less thing to chase from site.