Scaffolding Tools Insurance Theft Explained
Published on: September 14, 2026
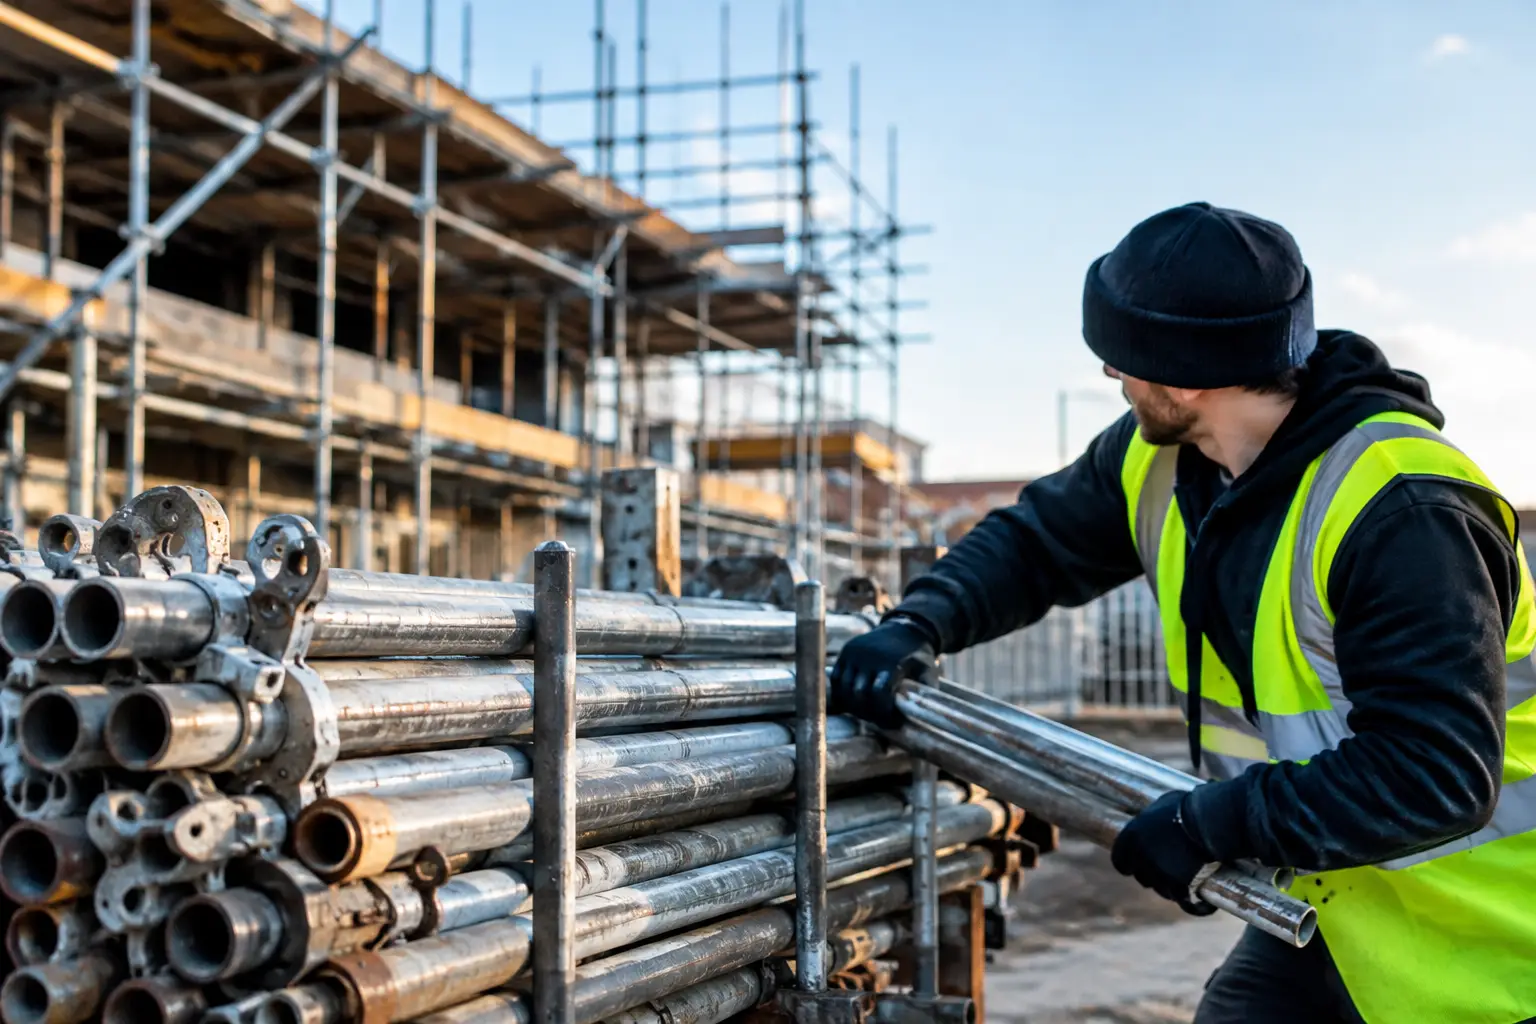
A forced van door, an empty lock-up or a site container found open at 6am can stop a scaffolding job before the crew has put the first lift up. Scaffolding tools insurance theft cover is there to help with that financial hit, but only when the policy, the security arrangements and the circumstances of the loss line up.
For a working scaffolder, tools are not a nice-to-have. They are what allow you to load out, erect safely, make adjustments and hand over a job on time. Replacing stolen kit at short notice can mean lost days, unhappy contractors and cash-flow pressure alongside the cost of the equipment itself. Duct tape cannot fix that.
What does tools insurance usually cover?
Tools and equipment insurance can protect items you own against insured events such as theft, accidental damage, fire and sometimes loss. The exact protection depends on the policy, so it is worth checking the wording rather than assuming every item is automatically covered in every location.
For scaffolders, insured equipment may include hand tools, power tools, lasers, drills, impact drivers, ratchets, spanners, harnesses, lanyards and smaller specialist gear. Some policies can also cater for portable generators or similar equipment, but larger assets may need to sit under own plant, hired-in plant or a separate equipment section instead.
That distinction matters. A small cordless tool set left in a locked vehicle is not treated in the same way as a telehandler, scaffold hoist or hired lifting equipment. Give your broker a clear picture of what you own, what you hire and the highest total value that could be at one location or in one vehicle.
The sum insured should reflect replacement cost, not what you paid for a well-used item years ago. Tool prices rise, and replacing several battery-powered tools, chargers and cases in one go can add up quickly. Underinsuring to reduce the premium can leave you funding part of the replacement bill yourself.
The theft conditions that can decide a claim
The most common surprise after a theft is not that a policy excludes theft altogether. It is that the equipment was left somewhere the policy does not cover, or a security condition was not met.
Many policies place tighter terms around tools left unattended in a vehicle. Cover may only apply if the vehicle is properly locked, tools are out of sight, and there is evidence of forced entry. Some insurers set time restrictions for overnight storage, require an alarm or immobiliser, or exclude tools left in a vehicle between certain hours. A van parked on a driveway overnight can be treated differently from a locked, alarmed compound.
Site storage needs the same attention. A locked steel container, site cabin or secure compound may be acceptable under a policy, while equipment left beneath a sheet, on an open scaffold or in an unsecured storage area is unlikely to be. Padlocks, hasps and container security should be fit for purpose, not simply present.
There can also be requirements around forced or violent entry. If a van was unlocked, a door was left ajar or tools were taken from an open work area, insurers may view the loss very differently. This is not about catching anyone out. Insurance is designed around an agreed level of reasonable care, and theft cover is priced on the basis that valuable equipment is secured when it is not being used.
Ask direct questions before buying or renewing: Are tools covered in a vehicle overnight? Does the cover apply at multiple sites? Is theft from a lock-up included? What security standard applies? Are employee-owned tools included? Straight answers at quotation stage are far easier than a dispute after a loss.
Tools, plant and hired equipment are not interchangeable
A scaffolding business often carries a mix of equipment, and putting it all under a generic “tools” heading can create gaps.
Tools insurance is generally intended for portable items. Own plant cover is more relevant for equipment your business owns that is larger, more valuable or used as plant. Hired-in plant cover can protect your contractual responsibility for equipment rented from another business, subject to the terms selected. Contract works cover is different again: it can protect work in progress and materials on a contract, rather than the hand tools used to do the work.
Think about a typical week. A crew may have drills and harnesses in the van, a generator in a locked container, hired plant on site and scaffold materials across several jobs. Each item has a different theft exposure and may need a different insurance answer. The right package depends on the business, the contracts you take on and where equipment is kept.
Reduce the chance of a theft – and make recovery easier
Security measures will not eliminate theft, particularly when organised gangs target trade vehicles and construction sites. They can, however, make your kit less attractive, help satisfy policy conditions and improve the chance of recovery.
A practical approach includes four basics:
- Keep an up-to-date inventory with photographs, serial numbers, make, model and replacement value.
- Mark tools visibly and, where suitable, use forensic marking or tracking technology on higher-value equipment.
- Remove valuable portable tools from vehicles overnight unless your insurance specifically allows secure overnight storage in the vehicle.
- Use quality vehicle locks, an alarm, immobiliser and a secure, well-lit storage area for vans, containers and lock-ups.
The inventory is often overlooked until it is needed. If several cases disappear after a break-in, trying to remember every drill, battery, laser and attachment from memory can slow a claim. Keep the record on a system you can still access if a phone, laptop or paperwork is also taken.
It is also sensible to brief the whole crew. One person may load the van, another may be last off site, and a subcontractor may use their own tools alongside yours. Agree who checks locks, who holds keys and where equipment must go at the end of the day. Clear routines reduce the chance that a rushed finish turns into an avoidable loss.
What to do when scaffolding tools are stolen
Act promptly, but do not rush into replacing everything before you understand what your policy requires. Start by making the area safe and preserving evidence. Take photographs of damage to the van, container or lock-up, including locks, doors and surrounding access points.
Report the theft to the police as soon as possible and obtain a crime reference number. Notify your insurer or broker without unnecessary delay, then provide the tool list, proof of ownership where available, purchase invoices, serial numbers and photographs. If CCTV may have captured the incident, request that footage is retained quickly because many systems overwrite recordings after a short period.
Be accurate when describing the loss. It is fine if you need time to compile a complete list, but avoid guessing at values or adding items that were not present. A clear, well-supported claim gives the claims handler a better starting point and can help move matters along.
If the theft leaves you unable to meet an urgent commitment, speak to the principal contractor early. You may be able to resequence work, borrow equipment safely or arrange hire while replacements are sourced. Check whether hire costs are insured before committing to them – they are not automatically part of every tools claim.
Buying cover that fits the way you work
Price matters, but the cheapest tools policy can be expensive if it excludes the place or time your equipment is most at risk. A sole trader who brings every tool indoors each night has different needs from a contractor running several vans, teams and live sites across a wide area.
When arranging cover, be ready to explain the value of your tools, where they are stored, the vehicles you use, whether equipment stays on site, and any previous thefts or claims. Mention hired equipment and larger plant too. This helps an insurance specialist place the risk with insurers whose terms suit scaffolding operations, rather than relying on assumptions.
Scaff Cover can help scaffolders review tools, plant and vehicle theft exposures alongside public liability and employers’ liability, so the cover reflects the way the business actually operates. The aim is not to load a policy with cover you do not need. It is to avoid finding out too late that a key piece of kit was in the wrong category or left in a location the policy did not permit.
Before the next van is loaded, take ten minutes to check the declared tool value, overnight storage terms and security requirements. That small check may be the difference between a theft being a serious disruption and a loss your business has to absorb alone.